Your Independent Medicare Advisor
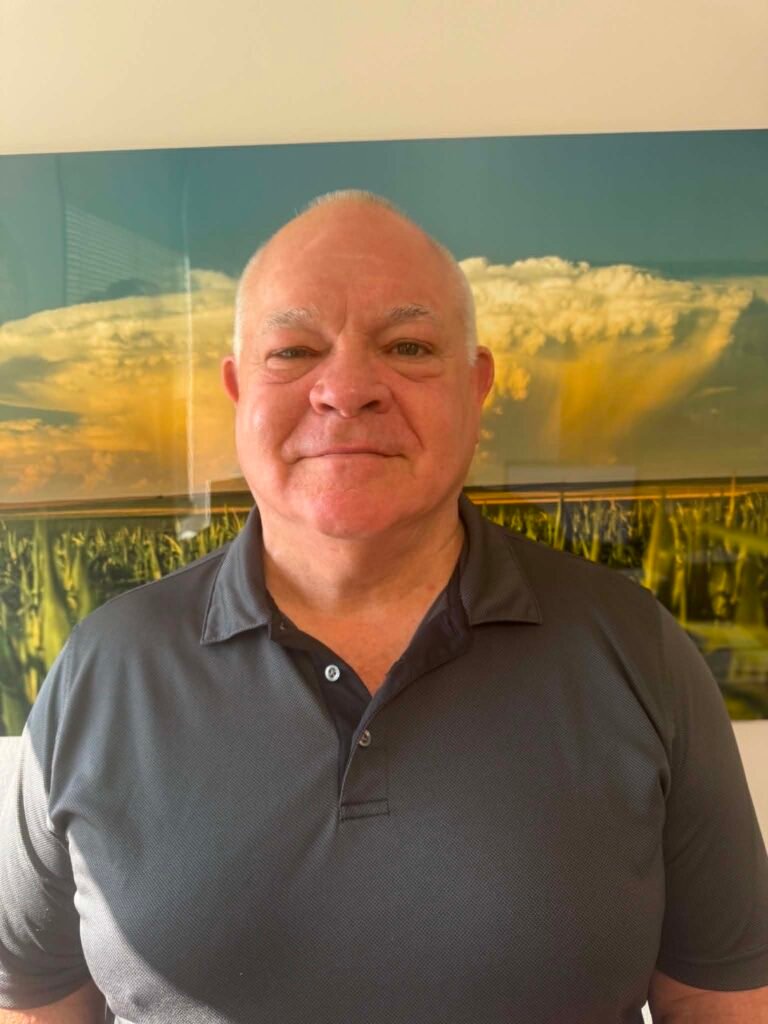
Eddie Langford
Founder of The Langford Insurance Group · Licensed Since 1994 · Independent Medicare Advisor
Medicare Supplement Meets the Difference
- Personalized Medicare Supplement guidance
- Compare plans, benefits & premiums
- Help with eligible Medicare costs
- Freedom to choose your healthcare providers
- Guidance from licensed Medicare professionals
What Is Medicare Supplement Insurance?
Original Medicare (Parts A and B) helps cover many of your healthcare costs, but you may still be responsible for deductibles, coinsurance, and certain copayments. These out-of-pocket expenses can add up, especially when you need significant medical care.
Medicare Supplement insurance, also called Medigap, is sold by private insurance companies and works alongside Original Medicare to help pay some of these remaining costs. You keep your Original Medicare coverage and can generally see any provider nationwide who accepts Medicare.
Medigap plans are standardized by the federal government, so plans with the same letter generally offer the same basic benefits regardless of the insurance company. However, premiums, underwriting, discounts, and other pricing factors can differ by carrier—which is why comparing available options can be valuable.
The goal is simple: understand your coverage, compare your options, and choose with confidence.
Your Medicare Journey, Made Simple.
Popular Choice for Comprehensive Coverage
Plan G
Plan G provides broad Medigap coverage for people eligible to purchase it. It covers many of the out-of-pocket costs left by Original Medicare, including Part A and Part B coinsurance, the Part A deductible, skilled nursing facility coinsurance, and certain foreign travel emergency costs.
- Part A coinsurance and hospital costs
- Part B coinsurance or copayments
- Part A deductible
- Part B excess charges, where applicable
- Skilled nursing facility coinsurance
- Foreign travel emergency care
Best for: People who want comprehensive Medigap coverage and more predictable out-of-pocket costs.
Important: For people newly eligible for Medicare, Plan G does not cover the Part B deductible. Also, Medigap benefits are standardized, but premiums and eligibility can vary by carrier and state.
Lower Premium Option
Plan N
Plan N provides comprehensive Medigap coverage while typically offering a lower monthly premium than Plan G. In exchange, you may pay copayments for certain office and emergency room visits, and the plan does not cover Part B excess charges.
- Part A coinsurance and hospital costs
- Part B coinsurance, subject to applicable copayments
- Part A deductible
- Skilled nursing facility coinsurance
- Foreign travel emergency care
- Does not cover Part B excess charges
Best for: People who want comprehensive Medigap coverage with a potentially lower monthly premium and are comfortable with some cost-sharing when they receive care
Note: Copayment amounts and other details can change based on applicable Medicare rules and the plan. Check the current plan materials for the exact amounts.
Lower Monthly Premium
High-Deductible Plan G
High-Deductible Plan G offers the same basic Medigap benefits as Plan G, but you pay covered Medicare cost-sharing amounts until you meet the plan’s annual deductible. After the deductible is met, the plan generally pays benefits according to Plan G rules.
- Plan G benefits after the annual deductible is met
- Typically a lower monthly premium than standard Plan G
- Annual deductible amount is set annually
- Part B excess charges
- Foreign travel emergency benefits
Best for: People who are comfortable with higher potential out-of-pocket costs in exchange for a lower monthly premium and want protection against larger covered Medicare expenses.
Note: The annual deductible and premiums can change from year to year. Always verify the current deductible and plan details before enrolling.
- No obligation · No cost · No call centers
Medicare Supplement vs. Medicare Advantage: What’s the Difference?
| Feature | Medicare Supplement (Medigap) | Medicare Advantage (Part C) |
|---|---|---|
|
Provider Choice |
See any doctor who accepts Medicare nationwide |
Use network providers (HMOs, PPOs) |
|
Out-of-Pocket Costs |
Minimal after premium and deductible |
May have copays, coinsurance, and out-of-pocket maximums |
|
Prescription Drugs |
Separate Part D plan needed |
Often included in Advantage plans |
|
Extra Benefits |
Limited |
May include dental, vision, hearing, fitness |
|
Travel Coverage |
Foreign travel emergency coverage (some plans) |
Emergency care usually in U.S. only |
When Can You Enroll in a Medicare Supplement Plan?
| Enrollment Period | Dates | Who Qualifies | What You Can Do |
|---|---|---|---|
|
Medicare Supplement Open Enrollment Period |
6-month period starting when you are 65 or older and enrolled in Part B |
Individuals newly enrolled in Medicare Part B at age 65+ |
Enroll in any Medicare Supplement plan available in your state without medical underwriting |
|
Guaranteed Issue Period |
Varies based on qualifying situation |
Individuals who lose certain coverage (e.g., employer coverage ends, Medicare Advantage plan leaves area) |
Enroll in specific Medigap plans without health questions or denial |
|
Outside Open Enrollment (Underwriting Required) |
Anytime after Open Enrollment ends |
Individuals applying after their 6-month Open Enrollment window |
Apply for coverage, but approval may require medical underwriting |
|
Trial Right Period |
Within first 12 months of enrolling in Medicare Advantage |
Individuals who want to switch back to Original Medicare |
May enroll in certain Medicare Supplement plans without underwriting |
Licensed since 1994
Helping Iowan navigate Medicare since 1998.
Truly Independent
Compare options from multiple insurance carriers not just one.
highly rated
Trusted by clients for personalized Medicare guidance.
Always Accessible
Real answers and personal support from a real Medicare professional.
Have questions about your options? I’m happy to walk you through them.
- No obligation · No cost · No call centers
Frequently Asked Questions
Your Medicare Questions, Answered
If you apply outside of your 6-month Medicare Supplement Open Enrollment Period (which begins when you are 65+ and enrolled in Part B), you may be required to go through medical underwriting. This means the insurance company can review your health history, potentially charge a higher premium, or deny coverage unless you qualify for guaranteed issue rights.
There is no fee to you for my Medicare guidance. If you enroll in a plan I represent, I may be compensated by the insurance carrier.
You don’t pay an additional fee for my services. No consultation fee. No obligation. No pressure.
Medicare Supplement plans (such as Plan G or Plan N) are standardized by the federal government, meaning benefits are the same regardless of the carrier. However, premiums can differ due to company pricing methods, administrative costs, customer service quality, financial strength, and historical rate increases.
With Medicare Supplement, you can generally see any doctor or specialist in the U.S. who accepts Medicare.
With Medicare Advantage, you typically need to use the plan’s network, although some plans may provide out-of-network coverage.
Before you enroll, I’ll help you check whether your preferred doctors and healthcare providers participate in the plan you’re considering.
Ready to Compare Your Medicare Options?
No pressure. No obligation. No cost for your consultation. Get straightforward guidance from an independent Medicare broker who can help you compare available options from multiple carriers.
Understand your choices. Compare your options. Choose with confidence.
- Licensed in FL, IA, IL, NV, KS, TN, MS, IN, NC, WI, VA · Independent · No cost to you